“I have only lost 200” cannot by itself establish a budget for another purchase. An already paid round may remain unsettled, or a separate purchase cap may already be exhausted despite an award coming back. One limit figure can hide other commitments.
In the JILI777 PH guides, budgeting controls spending rather than securing an expected win. The checkpoint below is our own fictional ledger. It does not describe an operator’s account limits, tools or availability.
Name each limit and its measurement period
Assume a fixed purchase cap of 500 in total confirmed debits during a chosen period. A separate personal net loss cap is 350. An award does not reset that purchase cap. All figures use the same illustrative unit, with no other fees or transactions.
₱150 lost. Why is the example cashback only ₱2? — Classify 20 eligible loss and 130 excluded loss before applying a hypothetical 10% rate. This is a model, not a verified offer or account claim.
A deposit cap measures something different again. A deposit moves money into an account; it is not automatically a stake, loss or return. State whether the period is a day, week or another interval. Do not pull transactions from outside that period to make its total look better.
Include payments that have not settled
| Item | Amount | Status |
|---|---|---|
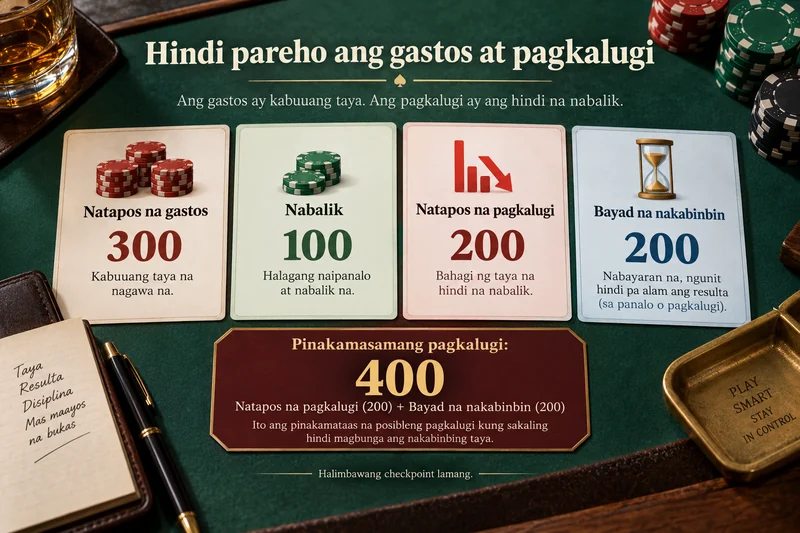
| Completed-round costs | 300 | Confirmed and settled |
| Their gross returns | 100 | Confirmed return |
| Completed net loss | 300 − 100 = 200 | Realised loss |
| Paid pending round | 200 | Debited; return unknown |
| Total confirmed debits | 300 + 200 = 500 | Purchase cap reached |
The total paid is already 500 even though realised loss is only 200. No allowance remains under the purchase cap. A return of 100 does not permit another purchase within the fixed personal cap we defined.
Account for unresolved exposure with a worst case
If the pending round returns nothing, total net loss becomes 200 + 200 = 400. That exceeds the loss cap of 350. “Another 150 before reaching 350” considers only settled loss and ignores the already paid exposure.
This does not claim that the pending return will actually be zero. Its outcome is unknown. The zero-return case shows how much could be lost from existing payments. An expected award, ongoing animation screenshot or promised bonus is not a confirmed return.
Both caps apply at the same time
Room of 100 under one cap and zero under another does not create a new allowance. In this model, the purchase cap is exhausted and final loss may exceed the loss cap because of an earlier pending payment. The cautious checkpoint decision is no further paid action while settlement is clarified.
The calculation does not justify raising a limit to accommodate pending exposure. Do not change the period or remove losing rows. If spending becomes uncomfortable, stop and use documented time-out, limit or support options actually available at the service; do not assume identical tools everywhere.
Locate an inconsistent total
A note saying total spending is 300 omits the confirmed pending debit of 200. A note saying loss is 500 fails to subtract the confirmed return of 100. In the zero-return pending case, loss is 400 while total debits are 500. Those figures answer different questions.
Keep transaction ID, measurement period, debit, return and settlement status for each row. A refund credit and a game award are different record types; a reversal is not a win. A promised refund should remain unresolved until a credit actually arrives.
Definitions, scope and a practical stopping point
UK Gambling Commission RTS 12 is a UK standard distinguishing deposit, spend and loss measures. It informs our labels, not a claim that identical legal requirements or platform tools apply in the Philippines. The two personal caps here are our own bookkeeping model.
This checkpoint leaves no allowance for a new purchase. Reconcile the pending record and retain the chosen limits. Return to JILI777 PH for other explanations; do not use essential household funds or borrowed money to pursue losses.